Retirement Planning for Entrepreneurs in Changing Times
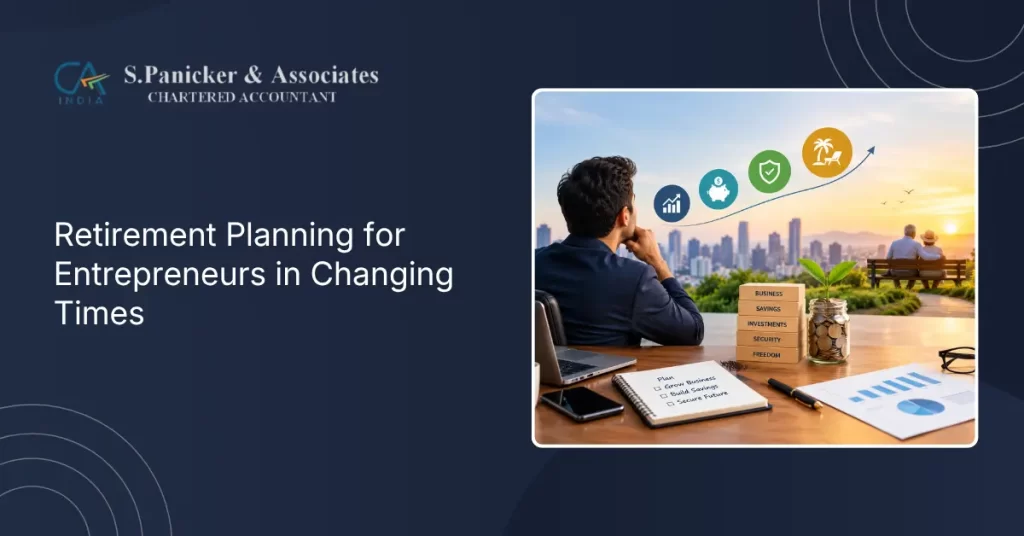
Ask any entrepreneur about their five-year business plan and they’ll have an answer ready. Ask about their retirement plan, though, and most just go quiet. Retirement Planning for Entrepreneurs tends to get pushed to “later” indefinitely, right up until later arrives faster than expected. And given how unpredictable things have gotten lately, that gamble isn’t really worth taking.
Why This Looks Nothing Like Employee Retirement Planning
Salaried folks have it a bit easier here. EPF gets deducted automatically, the employer adds their share, and retirement savings quietly build up without anyone thinking too hard about it.
Retirement Planning for Entrepreneurs: You’re On Your Own Here
There’s no such safety net for business owners. Nobody’s contributing on your behalf. No automatic deduction happens in the background while you focus on running things. Whatever retirement corpus you end up with, you built it yourself, deliberately, one decision at a time.
That’s basically why Retirement Planning for Entrepreneurs can’t just borrow the same playbook salaried employees use. It needs its own approach entirely.
Why It Matters Even More Right Now
The business landscape has shifted a lot compared to even a decade back. Industries get disrupted overnight, markets swing unpredictably, and income doesn’t always show up on schedule the way a salary does.
Some things entrepreneurs are dealing with these days:
- Income swings far more than a fixed monthly salary ever would
- Downturns hit self-employed people quicker and harder
- Pension schemes built for employees simply don’t apply here
- Healthcare costs keep climbing, and retirement money needs to stretch to cover that too
Given all this, treating Retirement Planning for Entrepreneurs like some tax-season afterthought just doesn’t work anymore. It needs actual, ongoing attention.
Mistakes Entrepreneurs Keep Making
Before getting into what actually works, it’s worth pointing out where things usually go wrong:
- Assuming the business itself will somehow fund retirement later
- Pouring every rupee back into the business, leaving nothing set aside personally
- Waiting for the business to feel “stable enough” before starting to save
- Mixing personal wealth with business assets, with no clear line between the two
- Forgetting inflation entirely while estimating future retirement needs
Chances are, at least one of these sounds familiar. Most business owners fall into one or two of these traps without even noticing until years later.
What Actually Works for Retirement Planning for Entrepreneurs
Here’s the thing – fixing this doesn’t need some dramatic overhaul. A handful of consistent habits does most of the heavy lifting.
Spread Your Money Around
Don’t let your business be your only asset. Try spreading things across:
- Mutual funds and equity
- Fixed deposits or debt instruments
- Real estate, if that suits your comfort level
- Retirement-specific options like NPS
Build a Separate Retirement Fund
Treat this like a non-negotiable monthly expense, not something you’ll “get to eventually.” Set up an automatic transfer into a dedicated retirement account so it happens whether business was good that month or brutal.
Revisit the Plan Every Year
Business circumstances shift constantly. What made sense two years back might not fit your situation today. Sit down once a year and adjust based on your income, market conditions, and whatever’s changed in life.
Bring In Professional Guidance Sooner Rather Than Later
This is where a lot of entrepreneurs slip up – trying to work out retirement numbers alone, without any real structure behind it. A chartered accountant in Kalyan West can help set realistic goals based on your actual income patterns, not generic assumptions.
Why Getting Expert Help Actually Changes Things
Retirement Planning for Entrepreneurs isn’t just about parking money somewhere safe. Tax implications, succession planning, timing of investments – all of it plays a part too.
A chartered accountant in Kalyan West understands how local businesses typically operate and can point you toward tax-efficient retirement options that actually fit your situation. A chartered accountant in Mumbai, meanwhile, brings exposure to entrepreneurs across all kinds of industries and income brackets, which helps when your business doesn’t fit any standard template.
Working with a chartered accountant in Kalyan West also means someone’s tracking tax rule changes on your behalf, keeping your plan compliant year after year without you having to chase updates yourself. If you’d rather have reliable guidance close by, Spanicker’s chartered accountant in Kalyan West services is worth checking out.
Final Thoughts
Retirement Planning for Entrepreneurs shouldn’t sit on hold until the business finally “settles down.” Truth is, most businesses never really settle completely, and waiting around for the perfect moment usually just means waiting too long. Start small, stay consistent, bring in expert advice early, and your future stays a lot more secure no matter how unpredictable things get.
Stay connected with S. Panicker & Associates for regular tax, GST and finance updates. Follow us on Facebook and Twitter, or message us anytime on WhatsApp.
Frequently Asked Questions
1. When’s the right time for entrepreneurs to start retirement planning?
As early as possible, ideally the moment income starts feeling steady. Waiting too long just makes catching up harder.
2. Can business profits alone take care of retirement?
Not really, no. Businesses go through rough patches, so separate retirement savings act as a cushion regardless of how the business is doing.
3. What’s a decent investment mix for entrepreneurs?
Usually a blend of equity, debt instruments, and something like NPS works well, though it really depends on your own risk comfort.
4. Is hiring a chartered accountant necessary for this?
It genuinely helps. A chartered accountant in Mumbai or Kalyan West can suggest tax-efficient strategies based on your specific business income.
5. How often should the plan get reviewed?
At least once a year, or whenever income, business direction, or life circumstances change significantly.
Recent Post
Registration of Partnership Firm in Maharashtra: Steps, Papers and Costs
Role of Asset Allocation in Achieving Your Financial Goals
Should You Outsource Accounting for Small Business in India? A Decision Guide with Real Numbers (2026)